Mortgage Financing. Made Easy.

David Sahibzada | Senior Mortgage Advisor

GET STARTED
If you're looking for mortgage financing, you've come to the right place. Let me help you find the best mortgage to meet your needs.

Mortgage financing can be confusing, it doesn't have to be, here's the plan.

Get started right away

The best place to start is to connect with me directly. The mortgage process is personal. My commitment is to listen to all your needs, assess your financial situation, and provide you with a clear plan forward.

Get a clear plan

Sorting through all the different mortgage lenders, rates, terms, and features can be overwhelming. Let me cut through the noise, I'll outline the best mortgage products available, with your needs in mind.

Let me handle the details

When it comes time to arranging your mortgage, I have the experience to bring it together. I'll make sure you know exactly where you stand at all times. No surprises. I've got you covered.
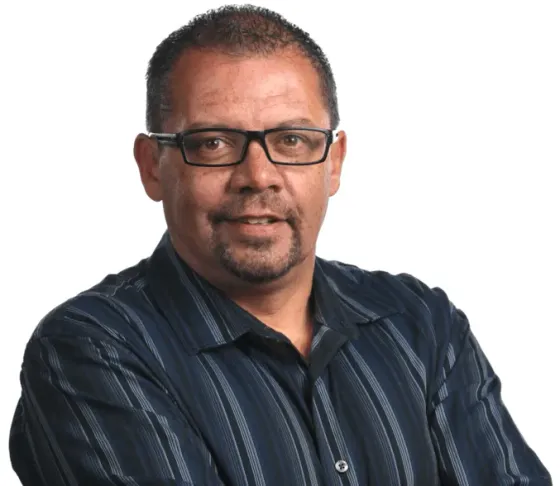
David Sahibzada

Senior Mortgage Advisor

Hello, my name is David Sahibzada and I'm here to help.


I first discovered Mortgage Brokering when my bank happily offered to renew my mortgage at over 7.00%. At the time I had a young family, one income, money was tight and I knew there was a better mortgage out there but I didn’t know how to find it. A friend referred me to a mortgage broker and I was able to get a much lower rate and a much better mortgage. That mortgage agent saved me thousands and I’m forever grateful for that referral I received!

For the past 15 years, it has been my turn to help. I know that sometimes the world of mortgages can be intimidating, complicated and confusing. I'm here to help you navigate through and find a solution that works for you. I'm good at what I do and have the skills and experience to save you time, effort and money! If you are looking for a friendly, easy to talk to mortgage expert please reach out anytime. 


I look forward to helping you...Dave

Contact me!

Here are some nice things clients have said about working with me.

Feel free to run some numbers.

Articles to keep you learning
By David Sahibzada September 15, 2026
So, you’re thinking about buying a home. You’ve got Pinterest boards full of kitchen inspo, you’re casually scrolling listings at midnight, and your friends are talking about interest rates like they’re the weather. But before you dive headfirst into house hunting— wait . Let’s talk about what “ready” really means when it comes to one of the biggest purchases of your life. Because being ready to own a home is about way more than just having a down payment (although that’s part of it). Here are the real signs you're ready—or not quite yet—to take the plunge into homeownership: 1. You're Financially Stable (and Not Just on Payday) Homeownership isn’t a one-time cost. Sure, there’s the down payment, but don’t forget about: Closing costs Property taxes Maintenance & repairs Insurance Monthly mortgage payments If your budget is stretched thin every month or you don’t have an emergency fund, pressing pause might be smart. Owning a home can be more expensive than renting in the short term—and those unexpected costs will show up. 2. You’ve Got a Steady Income and Job Security Lenders like to see consistency. That doesn’t mean you need to be at the same job forever—but a reliable, documented income (ideally for at least 2 years) goes a long way in qualifying for a mortgage. Thinking of switching jobs or going self-employed? That might affect your eligibility, so timing is everything. 3. You Know Your Credit Score—and You’ve Worked On It Your credit score tells lenders how risky (or trustworthy) you are. A higher score opens more doors (literally), while a lower score may mean higher rates—or a declined application. Pro tip: Pull your credit report before applying. Fix errors, pay down balances, and avoid taking on new debt if you’re planning to buy soon. 4. You’re Ready to Stay Put (At Least for a Bit) Buying a home isn’t just a financial decision—it’s a lifestyle one. If you’re still figuring out your long-term plans, buying might not make sense just yet. Generally, staying in your home for at least 3–5 years helps balance the upfront costs and gives your investment time to grow. If you’re more of a “see where life takes me” person right now, that’s totally fine—renting can offer the flexibility you need. 5. You’re Not Just Buying Because Everyone Else Is This one’s big. You’re not behind. You’re not failing. And buying a home just because it seems like the “adult” thing to do is a fast way to end up with buyer’s remorse. Are you buying because it fits your goals? Because you’re ready to settle, invest in your future, and take care of a space that’s all yours? If the answer is yes—you’re in the right headspace. So… Are You Ready? If you’re nodding along to most of these, amazing! You might be more ready than you think. If you’re realizing there are a few things to get in order, that’s okay too. It’s way better to prepare well than to rush into something you're not ready for. Wherever you’re at, I’d love to help you take the next step—whether that’s getting pre-approved, making a plan, or just asking questions without pressure. Let’s make sure your homebuying journey starts strong. Connect anytime—I’m here when you’re ready.
By David Sahibzada September 2, 2026
The Bank of Canada announced today that it is holding its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%. While Canada's economic recovery is broadening, a new layer of uncertainty has entered the picture. Here is what happened and what it means for your mortgage.
By David Sahibzada September 1, 2026
Saving for a down payment is one of the biggest challenges first-time buyers face. What many don’t realize is that the Canadian government offers a program designed to make it easier—the Home Buyers’ Plan (HBP) . This program allows you to withdraw money from your RRSP to help purchase your first home, without immediate tax consequences. Here’s how it works: Who Qualifies? To be eligible, you generally need to be a first-time home buyer. In practical terms, this means you must not have owned a home in the past four years, nor lived in a property owned by your spouse or partner during that time. There are also special allowances if you’re living with a disability or helping a relative with a disability. In these cases, you can use the HBP even if you’ve owned a home more recently. How Much Can You Withdraw? Under the program, you can access up to $35,000 from your RRSP as an individual. Couples can combine their withdrawals for a total of $70,000 . These funds must have been in your RRSP for at least 90 days before you take them out. Paying It Back The HBP isn’t “free money”—it’s an interest-free loan from your own retirement savings. You’ll have 15 years to repay the full amount back into your RRSP, starting in the second year after withdrawal. Each year, the CRA will send you an HBP Statement of Account outlining how much needs to be repaid. If you don’t make your repayment in a given year, that amount will be added to your taxable income. Why It’s a Smart Strategy The HBP can give first-time buyers a powerful boost toward homeownership. It helps you put together a larger down payment, which can reduce your mortgage amount and monthly payments. Just remember: it’s important to balance the short-term benefit of homeownership with the long-term impact on your retirement savings. Next Steps Thinking about using the Home Buyers’ Plan? Let’s sit down and review whether it’s the right move for you. Together, we can create a strategy that gets you into your first home while keeping your future financial goals on track. 📞 Reach out anytime—it would be a pleasure to guide you through the process.
Show More